To Spend, Or Not To Spend, That Is The Question
Every dollar that comes in eventually faces the same fork in the road: spend it now or set it aside for later. There is no single right answer, and no rule of thumb applies equally to every household. What can help is asking the right questions in the right order.
Start by knowing how much of your income is already committed. Housing, insurance, minimum debt payments, and other fixed costs come first. According to the Bureau of Economic Analysis, Americans saved 3.0% of their disposable income in July 2026. That figure is a reminder that after fixed costs and everyday spending, the amount left to save or spend can be a surprisingly small slice of a paycheck. Knowing that slice—and being honest about it—is the starting point. Separate “Can I?” From “Should I?”
Having enough money in your checking account answers only the first question. Whether a purchase is a good use of that money is a different question. A $3,000 vacation and a $3,000 addition to an emergency fund aren't directly comparable unless you know how much emergency savings you already have and how financially exposed you'd be without it. Affordability is about what you have. Good decision making is about what that money needs to accomplish.
Next, weigh what you're giving up. Every dollar spent is a dollar that can't also be saved, invested, or used to pay down debt. That doesn't make spending wrong. Spending is one of the reasons we work, save, and plan in the first place. It simply means that spending involves a trade-off. Before making a larger purchase, ask: What am I choosing not to do with this money instead? Sometimes putting the trade-off on paper makes the decision much clearer.
Match the decision to the timeline. When will you need the money? Money needed within the next one to three years generally belongs somewhere safe and accessible rather than in an investment that could lose value at an inconvenient time. Money that won't be needed for a decade or more can typically tolerate more time and investment risk. A house down payment due next spring and a grandchild's college fund needed in fifteen years are both forms of saving—but they call for different strategies.
Be cautious and watch for two warning signs. Two patterns are worth noticing at almost any income level: high-interest debt and lifestyle creep. Carrying credit card balances while continuing discretionary spending can work against long-term goals. And when expenses automatically rise with every increase in income, there may be little left to save. Neither is a moral failing; they're simply patterns worth recognizing.
Sometimes, “It depends” is the honest answer. Financial advice often comes wrapped in tidy rules, but real households rarely fit that neatly. The goal isn't to spend as little as possible or save every available dollar. The goal is to spend on purpose rather than by default.
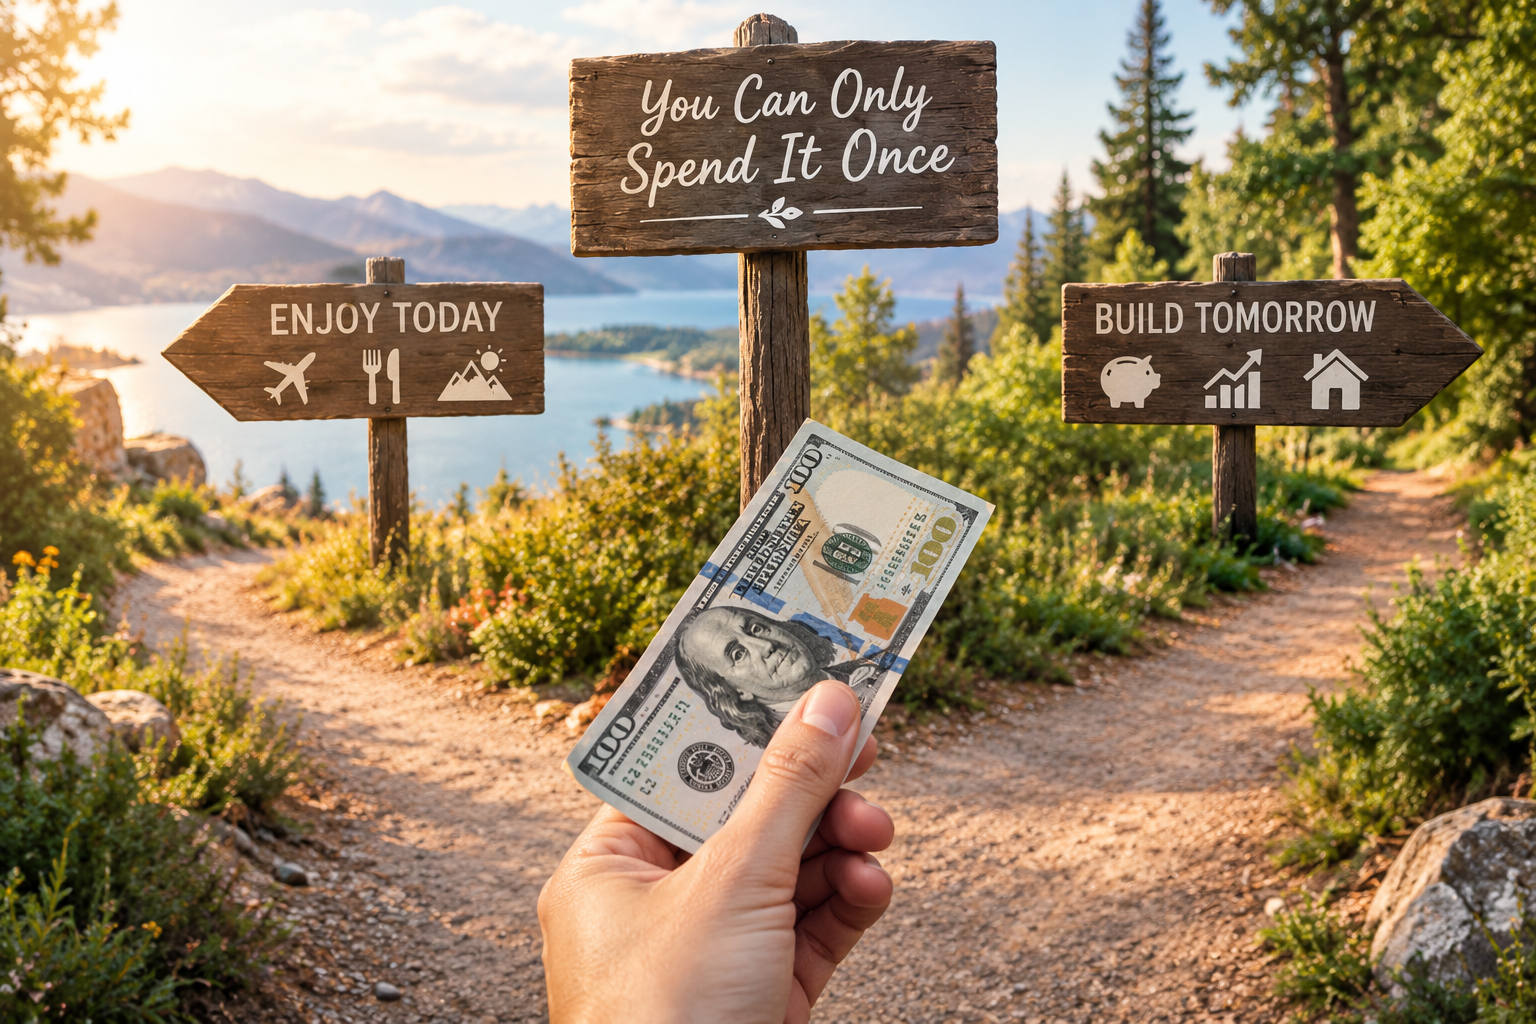
My mother had a simple way of putting it when she wanted to help me make wise decisions with my money: “You can only spend it once!” Sometimes that means enjoying money you've worked hard to earn. Sometimes it means saying no today so you have more choices tomorrow. The right answer is the one that fits your life, your priorities, and your timeline.
Post a comment